
Mastercard trades at $567.50 and has moved in lockstep with the market. Its shares have returned 13.4% over the last six months while the S&P 500 has gained 16.2%.
Is now a good time to buy MA? Find out in our full research report, it’s free.
Why Are We Positive on MA?
Recognizable by its iconic "Priceless" advertising campaign that has run in over 120 countries, Mastercard (NYSE:MA) operates a global payments network that connects consumers, financial institutions, merchants, and businesses, enabling electronic transactions and providing payment solutions.
1. Skyrocketing Revenue Shows Strong Momentum
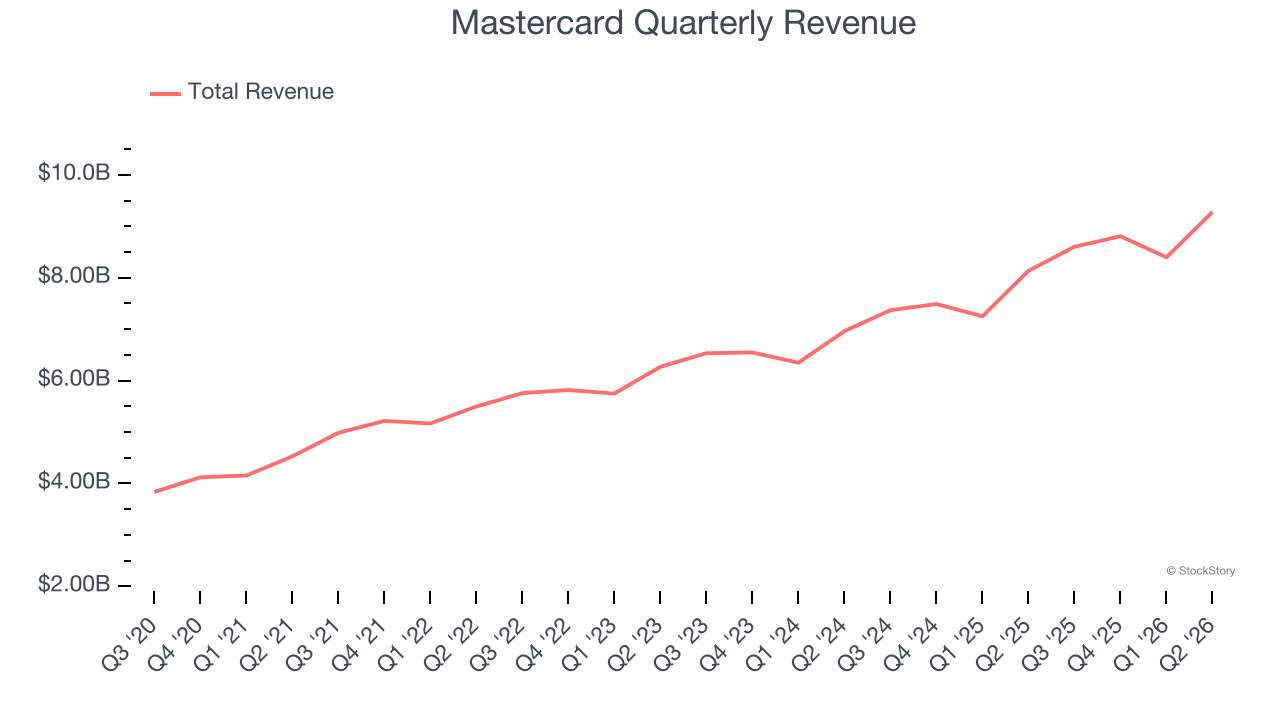
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
Over the last five years, Mastercard grew its revenue at an impressive 16.1% compounded annual growth rate. Its growth beat the average financials company and shows its offerings resonate with customers.
2. Outstanding Long-Term EPS Growth
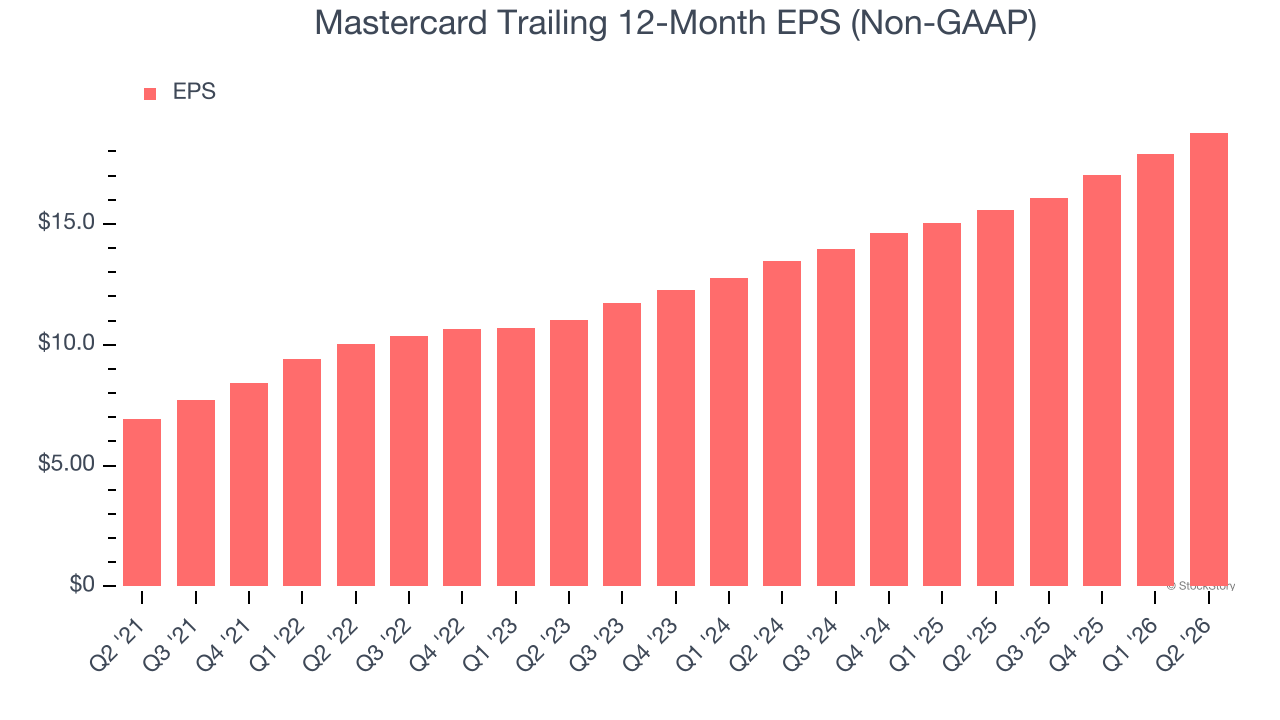
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Mastercard’s EPS grew at 22.1% compounded annual growth rate over the last five years, higher than its 16.1% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Stellar ROE Showcases Lucrative Growth Opportunities
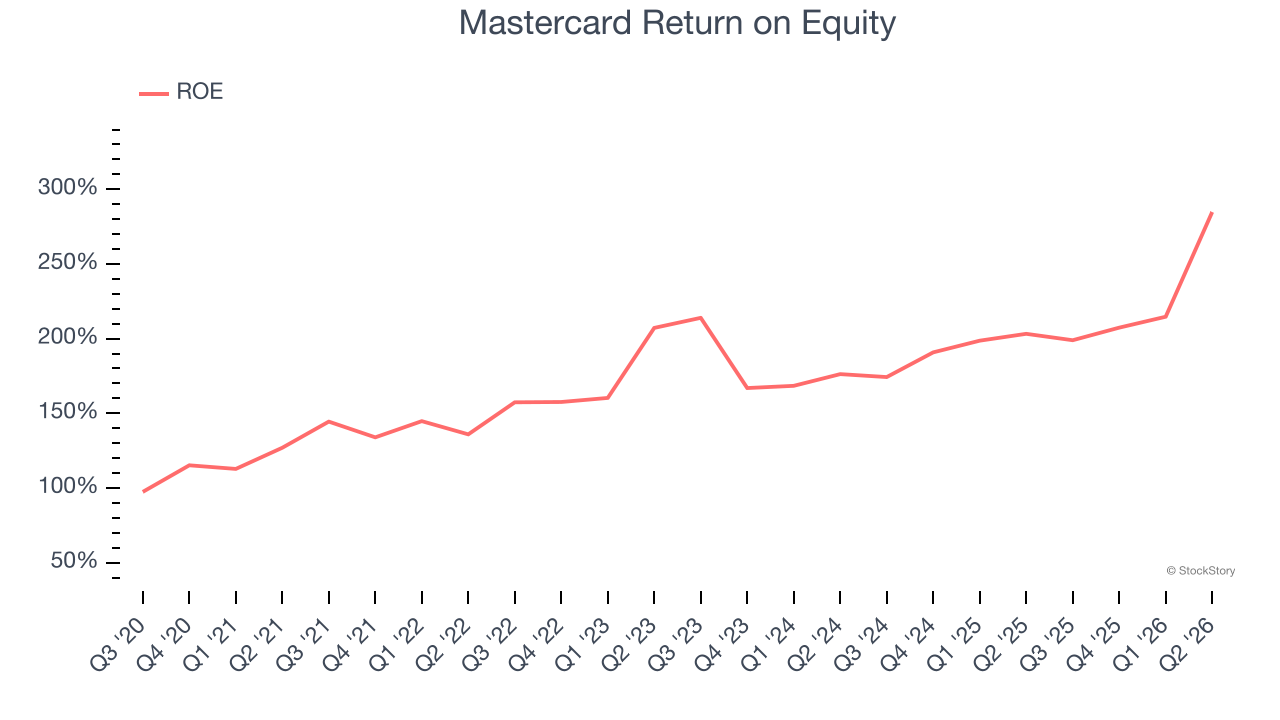
Return on equity (ROE) reveals the profit generated per dollar of shareholder equity, which represents a key source of financial firm funding. Financial firms maintaining elevated ROE levels tend to accelerate wealth creation for shareholders via earnings retention, buybacks, and distributions.
Over the last five years, Mastercard has averaged an ROE of 182%, exceptional for a company operating in a sector where the average shakes out around 10% and those putting up 25%+ are greatly admired. This shows Mastercard has a strong competitive moat.
Final Judgment
These are just a few reasons why Mastercard is a cream-of-the-crop financials company. At $567.50 per share (or 26.6× forward P/E), is now the time to initiate a position? See for yourself in our full research report, it’s free.
High-Quality Stocks for All Market Conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.